Battery Storage Investment: A Guide to the Emerging Asset Class
Explore battery storage investment, including revenue models, technology risks, regulations, financial structures, and essential investor due diligence.
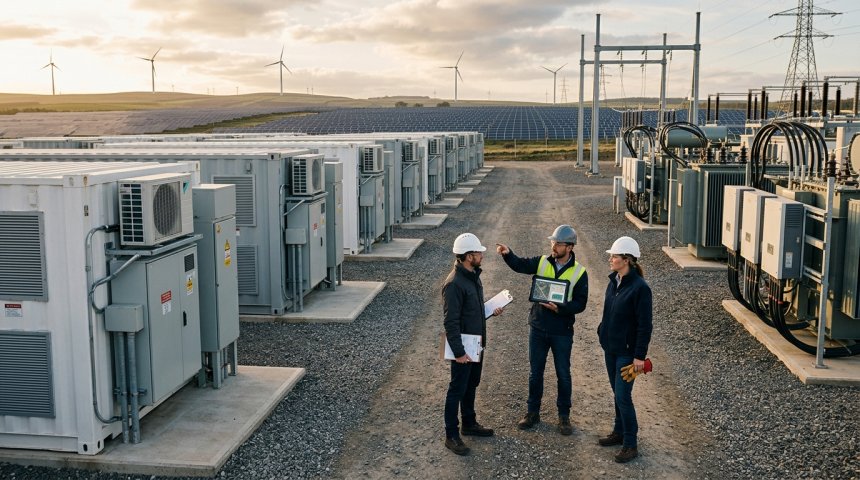
Battery energy storage has crossed the threshold from niche technology demonstration to mainstream infrastructure asset class in less than a decade. Global deployed capacity exceeded 100 GWh annually by 2025, project-level economics have achieved grid parity in dozens of markets without subsidies, and institutional capital now flows into storage with the same analytical rigor previously reserved for solar, wind, and natural gas generation. Yet despite this maturation, battery storage remains fundamentally different from traditional power assets in ways that catch unprepared investors off guard. The revenue streams are more complex and volatile. The technology degrades predictably but irreversibly. The regulatory landscape evolves faster than project lifecycles. The supply chain concentrates geopolitical risk in unfamiliar ways. And the financial models require assumptions about electricity market design, battery degradation curves, and augmentation strategies that most infrastructure investors haven't encountered before.
For institutional investors, private equity firms, infrastructure funds, family offices, and corporate strategists evaluating battery storage allocations, understanding these differences isn't optional—it's the prerequisite for avoiding costly mispricing, operational surprises, and stranded assets. The investors capturing outsized returns in this space aren't those who simply believe in the energy transition thesis; they're those who understand the granular mechanics of how storage projects actually generate cash flow, what can go wrong, and how to structure investments that align risk with return across technology, market, and regulatory dimensions.
This guide provides that granular understanding. We'll dissect the revenue model architecture that makes storage bankable, examine technology risks and mitigation strategies that separate viable projects from science experiments, map the regulatory and policy frameworks creating or destroying value across jurisdictions, analyze financial structuring approaches matching storage's unique cash flow characteristics, evaluate supply chain and procurement considerations affecting project economics, and establish due diligence frameworks enabling confident capital deployment. Whether you're evaluating your first storage investment, scaling an existing portfolio, advising clients on energy transition exposure, or assessing storage's role in broader infrastructure allocation, this analysis delivers the technical depth and commercial context needed to navigate this emerging asset class with discipline rather than enthusiasm alone.
Let's begin by establishing why battery storage qualifies as a distinct asset class rather than merely an adjunct to renewable generation—and why that distinction matters for investment approach.
Chapter 1: Battery Storage as Distinct Asset Class — Why It Matters
Treating battery storage as "solar plus" or "wind ancillary" leads to fundamental mispricing. Storage has unique economic characteristics requiring dedicated analytical frameworks.
Revenue Model Complexity vs. Traditional Generation
Traditional renewable generation earns revenue primarily through energy sales (PPAs or merchant) with predictable production profiles correlated to resource availability. Battery storage earns revenue through multiple simultaneous value streams that vary temporally, contractually, and regulatorily:
Energy Arbitrage: Charging during low-price periods and discharging during high-price periods. Revenue depends on price spread volatility, round-trip efficiency, and cycling frequency. Unlike generation, arbitrage revenue is inherently variable and market-dependent.
Capacity Payments: Compensation for committed availability during system peak or contingency events. Capacity markets exist in some jurisdictions (PJM, ISO-NE, UK CM) but not others. Payment structures vary (auction-based, administratively set, bilateral). Capacity revenue often provides baseline cash flow supporting debt service but represents only portion of total value stack.
Ancillary Services: Frequency regulation, voltage support, spinning/non-spinning reserves, black start capability. Historically highest-margin storage revenue stream but increasingly saturated as storage deployment grows. Service requirements and compensation mechanisms differ significantly across grid operators. Technical capability must match service specifications precisely; non-compliance triggers penalties.
Transmission and Distribution Deferral: Utilities compensate storage for deferring or avoiding traditional infrastructure upgrades. Contractual, long-duration revenue but limited opportunity set tied to specific grid constraints. Regulatory approval required; political risk if ratepayer advocates challenge prudence.
Resource Adequacy and Reliability Services: Emerging compensation for providing firm capacity during extreme weather or contingency events. California RA, Texas ECRS, and similar mechanisms create new revenue categories. Definitions and eligibility evolving rapidly; early movers capture premium but face regulatory uncertainty.
Environmental Attribute Monetization: In some jurisdictions, storage generates tradable credits (RECs, ZECs, carbon allowances) when paired with renewables or displacing fossil generation. Credit values volatile and policy-dependent. Stacking environmental attributes with other revenue streams requires careful contractual and regulatory navigation.
This multi-stream complexity means storage project valuation cannot rely on single-metric analysis (e.g., $/MWh PPA price). Investors must model revenue stack composition, correlation between streams, saturation risk, and regulatory durability. Projects optimized for one revenue stream may underperform when that stream saturates; diversified revenue stacks provide resilience but increase modeling and operational complexity.
Degradation as Fundamental Economic Parameter
Unlike solar panels that degrade slowly and predictably (~0.5%/year), batteries experience throughput-dependent degradation directly tied to revenue-generating activity. More cycling equals more revenue but also more degradation. This creates fundamental tension absent from generation assets: maximizing near-term revenue accelerates long-term value erosion.
Investment models must explicitly account for:
- Degradation curves: Non-linear capacity fade dependent on depth of discharge, charge/discharge rates, temperature, and chemistry. Manufacturer warranties provide floor guarantees but actual degradation varies with operational profile.
- Augmentation strategy: Planned battery replacement or addition maintaining capacity over project life. Augmentation timing, cost, and technology refresh assumptions critically impact long-term economics. Underestimating augmentation needs destroys terminal value; overestimating inflates upfront capital.
- Warranty vs. actual performance gap: Warranties define minimum acceptable performance; actual performance determines revenue. Gap between warranty floor and expected performance represents upside potential or downside risk depending on operational execution.
- End-of-life residual value: Second-life applications, recycling revenue, or disposal costs affect terminal value. Recycling economics improving but remain uncertain over 15-20 year project horizons. Residual value assumptions should be conservative; upside captured if realized.
Degradation modeling requires electrochemical expertise beyond typical infrastructure investment teams. Engaging independent engineers with battery-specific experience isn't optional; it's essential for credible cash flow projections.
Technology Risk Profile Distinct from Mature Assets
Solar and wind technologies have decades of operational history validating performance assumptions. Battery storage technology evolves on annual cycles with meaningful differences between generations:
Chemistry evolution: LFP (lithium iron phosphate) displacing NMC (nickel manganese cobalt) for stationary storage due to safety, cycle life, and cost advantages despite lower energy density. Sodium-ion emerging as lower-cost alternative for less demanding applications. Flow batteries targeting long-duration niche. Each chemistry has distinct degradation characteristics, safety profiles, supply chains, and cost trajectories. Technology selection locks in performance parameters for project lifetime; wrong choice creates structural disadvantage.
System integration maturity: Battery management systems (BMS), thermal management, power conversion, and controls software determine real-world performance more than cell specifications alone. Integration quality varies significantly across providers. Poorly integrated systems underperform nameplate ratings, degrade faster, and experience more downtime. System integrator track record matters as much as cell supplier reputation.
Safety and insurance evolution: Thermal runaway incidents have reshaped industry standards, insurance pricing, and permitting requirements. NFPA 855, UL 9540A, and evolving codes impose spacing, suppression, and monitoring requirements increasing project cost. Insurance premiums reflect loss experience and remain volatile. Safety incidents anywhere in industry affect all projects through insurance repricing and regulatory response.
Technology risk isn't binary (works/doesn't work); it's continuous spectrum of performance certainty. Investors must calibrate technology confidence against project economics and risk tolerance. First-of-kind technology offers potential upside but carries validation risk; proven technology offers predictability at potentially higher cost.
Key Insight: For authoritative baseline data on battery storage deployment trends, cost trajectories, and operational performance across U.S. markets, the U.S. Energy Information Administration (EIA) Battery Storage Reports provides regularly updated government statistics essential for benchmarking investment assumptions against observed market outcomes.
Chapter 2: Revenue Stack Architecture — Modeling Cash Flow Realistically
Storage project bankability depends on credible revenue modeling reflecting actual market mechanics rather than theoretical value stacks.
Revenue Stream Hierarchy and Bankability
Not all revenue streams carry equal weight in financing and valuation:
Contracted Revenue (Highest Bankability): Long-term contracts (capacity agreements, tolling arrangements, utility PPAs) with creditworthy counterparties provide predictable cash flow supporting debt. Tenor typically 10-20 years. Credit quality of counterparty determines debt capacity; investment-grade utilities enable lowest-cost capital. Contract structure matters: fixed payments most bankable; indexed or performance-based payments introduce variability reducing debt capacity.
Quasi-Contracted Revenue (Moderate Bankability): Market-based revenue with structural predictability. Capacity auction clearing prices, regulated tariff rates, or formulaic ancillary service compensation provide reasonable visibility despite lacking bilateral contract. Bankability depends on market design stability and historical price persistence. Lenders apply haircuts reflecting uncertainty; equity absorbs residual risk.
Merchant Revenue (Lowest Bankability): Pure spot market exposure to energy and ancillary service prices. Highest upside potential but greatest volatility. Difficult to finance with debt; typically equity-funded or supported by contracted revenue base. Merchant revenue modeling requires sophisticated stochastic simulation capturing price correlations, volume risk, and operational constraints. Backtesting against historical data validates model assumptions but doesn't guarantee future performance.
Revenue Stack Optimization: Most bankable projects combine contracted base with merchant upside. Typical target: 60-80% contracted revenue covering debt service and fixed costs; 20-40% merchant revenue providing equity return uplift. Exact mix depends on market maturity, counterparty availability, and investor risk appetite. Over-contracting leaves money on table; under-contracting jeopardizes debt coverage. Optimization is dynamic; renegotiation opportunities arise as markets evolve.
Market-Specific Revenue Dynamics
Storage economics vary dramatically by geography due to market design, regulatory frameworks, and grid characteristics:
PJM (U.S. Mid-Atlantic): Mature capacity market providing stable baseline revenue. Regulation market historically lucrative but saturating with storage entry. Energy arbitrage moderate due to relatively flat price curves. Strong interconnection queue but lengthy timelines. Well-understood by lenders enabling efficient financing.
CAISO (California): High renewable penetration creating significant arbitrage opportunities and evening ramp needs. Resource adequacy framework evolving with storage-specific products. Wildfire and public safety power shutoff events creating reliability premium. Regulatory complexity increases transaction costs but also creates barriers to entry protecting incumbents.
ERCOT (Texas): Pure merchant market with no capacity mechanism. Extreme price volatility during scarcity events creates massive arbitrage and reliability service value. Higher revenue potential but greater uncertainty. Winter Storm Uri demonstrated both opportunity and risk. Financing more expensive reflecting merchant risk; equity-heavy capital structures common.
UK National Grid: Capacity Market providing long-term revenue certainty. Balancing Mechanism and Dynamic Containment services offering additional revenue. CfD framework potentially extending to storage. Mature market with established financing precedents. Brexit-related regulatory divergence creating ongoing uncertainty.
Australian NEM: High renewable penetration driving frequency control and arbitrage demand. FCAS markets lucrative but volatile. State-based schemes adding revenue layers. Transmission constraints creating locational value differentiation. Market reform ongoing introducing new opportunities and risks.
Each market requires bespoke revenue modeling reflecting local rules, participant behavior, and evolution trajectory. Cross-market generalizations dangerous; assumptions validated per jurisdiction.
Revenue Risk Factors and Mitigation
Saturation Risk: As storage deploys, marginal value of additional storage declines. Ancillary service markets saturate first; energy arbitrage follows. Mitigation: secure long-term contracts before saturation; diversify revenue streams; locate in constrained areas with persistent value; select technology capable of accessing multiple markets.
Regulatory Change Risk: Market rules evolve; today's revenue stream may disappear or transform tomorrow. Mitigation: contract for defined services rather than assumed market structures; negotiate change-in-law provisions; maintain regulatory monitoring capability; diversify across jurisdictions reducing single-market exposure.
Counterparty Credit Risk: Contracted revenue depends on counterparty solvency. Utility bankruptcies (PG&E precedent) demonstrate real risk. Mitigation: require investment-grade counterparties or credit support; negotiate termination rights and collateral provisions; diversize counterparties; consider political risk insurance for municipal/public entities.
Operational Performance Risk: Actual revenue depends on availability, efficiency, and dispatch optimization. Underperformance reduces cash flow. Mitigation: O&M contracts with performance guarantees; liquidated damages for availability shortfalls; independent engineering validation of performance assumptions; reserve accounts covering underperformance risk.
Cannibalization Risk: Own storage fleet competing against itself in merchant markets. Mitigation: coordinated dispatch optimization across portfolio; contractual allocation of merchant revenue; geographic diversification reducing self-competition.
Chapter 3: Technology Due Diligence — Beyond Nameplate Specifications
Technology assessment requires looking past marketing materials to validated performance under realistic operating conditions.
Cell and Module Level Evaluation
Chemistry Selection Rationale: Verify chemistry choice aligns with application requirements. LFP preferred for daily cycling stationary storage due to longer cycle life, better thermal stability, and lower cost despite lower energy density. NMC appropriate where space constrained or higher energy density justified. Sodium-ion emerging for cost-sensitive, lower-performance applications. Chemistry mismatch to use case creates structural economic disadvantage. Request test data validating chemistry performance under projected operating profile.
Cycle Life Validation: Manufacturer cycle life claims based on standardized test conditions rarely match field performance. Request accelerated aging test data at relevant temperatures, depths of discharge, and C-rates. Independent third-party testing preferred over manufacturer self-reporting. Warranty terms reveal manufacturer confidence; aggressive warranties suggest validated performance; conservative warranties signal uncertainty. Compare warranty degradation curves against revenue model assumptions; gaps indicate either overly optimistic modeling or unnecessarily conservative warranty.
Thermal Management Assessment: Thermal management system design critically impacts degradation rate, safety, and parasitic load. Liquid cooling superior to air cooling for high-cycling applications but adds complexity and maintenance. Evaluate thermal uniformity across module/pack; hot spots accelerate localized degradation. Parasitic energy consumption reduces round-trip efficiency; quantify and incorporate into revenue model. Thermal management redundancy and failure modes assessed; single-point failures unacceptable.
BMS and Controls Sophistication: Battery management system determines real-world performance more than cell quality alone. Evaluate BMS capabilities: state-of-charge/state-of-health estimation accuracy, cell balancing effectiveness, thermal management coordination, fault detection and response, communication protocols, and cybersecurity. Proprietary BMS creates vendor lock-in; open architectures enable flexibility. Software update capability ensures ongoing optimization; obsolete software strands assets. Reference checks with existing operators reveal BMS reliability and support quality.
System Integration and Balance of Plant
Inverter/PCS Selection: Power conversion system efficiency, reliability, and grid compliance determine revenue capture. Evaluate round-trip efficiency at various load points (not just nameplate peak). Assess grid code compliance across target markets; non-compliance prevents interconnection or triggers curtailment. Redundancy and modularity enable partial operation during failures. Spare parts availability and service response times affect availability. PCS supplier financial stability matters; orphaned equipment becomes liability.
Enclosure and Environmental Protection: Enclosure design affects thermal performance, maintenance access, safety, and longevity. Evaluate IP rating appropriate for site conditions. Corrosion protection adequate for coastal or industrial environments. Maintenance access enables component replacement without full system shutdown. Fire suppression integration meets current codes and insurance requirements. Enclosure standardization across fleet simplifies O&M; custom designs increase lifecycle cost.
Balance of Plant Quality: Transformers, switchgear, cabling, and civil works represent significant cost and failure risk. Evaluate equipment specifications against industry standards. Supplier qualifications verified. Installation quality assured through inspection protocols. BoP failures cause extended downtime; quality investment pays through availability.
Safety and Compliance Verification
Testing and Certification: Verify UL 9540, UL 9540A, IEC 62619, UN38.3, and applicable certifications completed. Test reports reviewed by independent engineer confirming relevance to proposed configuration. Certifications specific to exact system configuration; modifications may invalidate certification. Testing currency matters; standards evolve and older tests may not satisfy current requirements.
Fire Risk Assessment: Comprehensive fire risk analysis addressing prevention, detection, suppression, and containment. Spacing compliance with NFPA 855 and local amendments. Suppression system design validated through testing. Off-gas detection and ventilation adequate. Emergency response plan developed and coordinated with local authorities. Insurance carrier review completed confirming insurability and premium acceptability. Fire risk assessment living document updated as standards and experience evolve.
Transportation and Handling Compliance: Battery transportation subject to hazardous materials regulations. Verify compliance with DOT, IATA, IMDG as applicable. Packaging, labeling, and documentation correct. Carrier qualifications verified. Transportation incidents create liability and delay; compliance non-negotiable.
Chapter 4: Financial Structuring — Matching Capital to Cash Flow Characteristics
Storage's unique cash flow profile requires tailored financial structures differing from traditional generation.
Debt Structuring Considerations
Debt Capacity Determinants: Storage debt capacity driven by contracted revenue quality, not asset value. Lenders focus on debt service coverage ratio (DSCR) calculated from contracted cash flows after operating expenses and reserves. Typical DSCR minimum 1.20-1.30x. Merchant revenue receives minimal or no debt credit unless hedged or demonstrating sustained track record. Debt sizing conservative reflecting technology and market risk; leverage typically 50-70% of eligible contract value versus 70-85% for mature renewables.
Tenor and Amortization: Debt tenor aligned with contract duration but typically shorter reflecting technology risk. 10-15 year tenors common versus 20-25 years for solar/wind. Amortization sculpted to match contracted revenue profile; front-loaded amortization if contracts back-weighted. Tail period beyond contract expiry requires refinancing or merchant revenue assumption; tail risk priced into terms or mitigated through reserves.
Reserve Accounts: Multiple reserves address storage-specific risks: debt service reserve (6-12 months), maintenance reserve (augmentation funding), revenue stabilization reserve (merchant volatility buffer), and contingency reserve (unforeseen events). Reserve sizing reflects project risk profile; higher-risk projects require larger reserves reducing distributable cash flow but enhancing debt sustainability. Reserve release triggers negotiated with lenders balancing flexibility and protection.
Covenants and Reporting: Financial covenants include minimum DSCR, liquidity ratios, and performance thresholds. Technical covenants address warranty compliance, maintenance standards, and reporting requirements. Reporting frequency higher than traditional assets reflecting technology evolution and market dynamism. Covenant breaches trigger remediation periods before default; cure mechanisms negotiated upfront.
Equity Return Expectations and Waterfall Structures
Return Profile: Storage equity returns typically 10-18% unlevered IRR depending on risk profile. Contracted-heavy projects target lower end; merchant-exposed projects target higher end. Returns compensate for technology risk, market evolution uncertainty, and operational complexity exceeding mature renewables. Return expectations calibrated against risk-adjusted alternatives; overpaying for perceived growth destroys value.
Waterfall Complexity: Storage waterfalls often more complex than generation reflecting multiple revenue streams, augmentation funding, and performance incentives. Typical priorities: operating expenses → debt service → reserve funding → preferred equity return → sponsor equity return → residual split. Augmentation reserves funded before distributions ensuring lifecycle viability. Performance-based incentive allocations align operator interests with investor returns. Waterfall negotiation balances investor protection with operator motivation.
Tax Equity and Incentive Monetization: U.S. Investment Tax Credit (ITC) now available for standalone storage under IRA. Tax equity structures enable monetization by investors with tax appetite. Partnership flip, sale-leaseback, and inverted lease structures adapted for storage. ITC eligibility requires meeting prevailing wage and apprenticeship requirements; compliance documentation essential. State and local incentives stack with federal benefits but add compliance complexity. Tax equity market for storage maturing but less liquid than solar; pricing reflects novelty premium.
Augmentation Financing Strategies
Battery augmentation represents significant mid-life capital expenditure requiring advance planning:
Upfront Reserve Funding: Funding augmentation through initial capital raise and reserve accumulation. Advantages: certainty of funding, avoids refinancing risk. Disadvantages: capital locked in reserve earning below-project returns, overfunding risk if technology improves or costs decline. Reserve sizing based on degradation model and cost forecast with sensitivity analysis.
Refinancing at Augmentation Point: Refinancing existing debt or raising new equity at augmentation milestone. Advantages: preserves initial capital efficiency, captures technology cost improvements. Disadvantages: refinancing risk if market conditions deteriorate, potential covenant restrictions. Pre-negotiated augmentation facilities reduce uncertainty; optionality valuable even if unused.
Vendor Financing: Equipment suppliers offering augmentation financing tied to original supply agreement. Advantages: simplified procurement, aligned incentives. Disadvantages: potentially higher cost, vendor lock-in, limited flexibility. Vendor financing evaluated against market alternatives; competitive tension maintained.
Performance-Based Augmentation: Augmentation triggered by actual degradation rather than predetermined schedule. Advantages: aligns spending with need, captures better-than-expected performance. Disadvantages: uncertainty complicates financial planning, potential warranty conflicts. Requires robust monitoring and clear trigger definitions.
Chapter 5: Supply Chain and Procurement Risk Management
Battery supply chain concentration creates strategic risks requiring active management.
Critical Mineral Exposure
Lithium, cobalt, nickel, graphite, and manganese supply chains concentrate geographically creating geopolitical and pricing risk:
Geographic Concentration: China dominates refining (60-80% across minerals) and cell manufacturing (>75%). Mining more diversified but still concentrated (Australia lithium, DRC cobalt, Indonesia nickel). Geopolitical tensions, trade restrictions, or domestic policies in producing countries disrupt supply. Diversification efforts underway but take years to scale.
Price Volatility: Battery mineral prices experienced 300-500% swings during 2021-2023 cycle. Price pass-through mechanisms in supply contracts allocate risk between buyer and seller. Fixed-price contracts provide certainty but embed premium; indexed pricing tracks market but exposes to volatility. Hybrid structures balance predictability with fairness. Price hedging instruments emerging but illiquid for many minerals.
ESG and Traceability Requirements: Increasing regulatory and customer demands for responsible sourcing. EU Battery Regulation, U.S. Uyghur Forced Labor Prevention Act, and corporate ESG commitments require supply chain transparency. Compliance adds cost and complexity but also creates differentiation. Blockchain and passport initiatives improving traceability but immature. Non-compliance risks market access restrictions and reputational damage.
Manufacturing Capacity and Lead Times
Cell Supply Constraints: Despite massive capacity expansion announcements, qualified cell supply remains constrained for premium applications. Tier 1 manufacturers prioritize large, long-term customers. Spot purchases carry price and quality risk. Securing allocation requires relationship building, volume commitment, and sometimes equity participation. Supply agreements negotiated 12-24 months ahead of project COD; late procurement forces suboptimal choices.
Integration Bottlenecks: System integrators assembling cells into modules, packs, and complete systems represent bottleneck. Qualified integrator capacity limited relative to demand. Lead times 6-18 months depending on backlog. Integrator selection critical; poor integration undermines cell quality. Reference checks and factory audits essential. Multi-integrator strategy reduces dependency but increases management complexity.
Domestic Content and Localization: IRA domestic content bonuses and foreign entity of concern restrictions incentivize U.S./FTA-country manufacturing. Domestic capacity building but years from matching Asian scale and cost. Localization premiums currently 10-30% but declining as capacity scales. Domestic content qualification complex; expert advisory recommended. Policy interpretation evolving; flexibility preserved through modular supply chain design.
Procurement Strategy Best Practices
Multi-Supplier Approach: Avoiding single-supplier dependency through dual-sourcing cells, inverters, and integration. Primary supplier secured for volume; secondary supplier qualified for flexibility. Qualification cost justified by risk reduction. Supplier diversification balanced against volume discount benefits.
Long-Term Framework Agreements: Master supply agreements establishing terms, pricing mechanisms, and volume commitments across multiple projects. Framework agreements reduce per-project negotiation time and secure preferential treatment. Flexibility provisions accommodate project pipeline uncertainty. Relationship investment yields priority allocation during shortages.
Index-Linked Pricing Mechanisms: Contract pricing linked to transparent indices (Fastmarkets, Benchmark Minerals, S&P Platts) rather than opaque negotiations. Index linkage ensures fair market pricing and reduces dispute risk. Collar provisions limit extreme exposure. Index selection critical; liquidity and representativeness verified.
Quality Assurance Protocols: Incoming inspection, batch testing, and factory acceptance testing specified in supply agreements. Third-party inspection rights negotiated. Quality defect remedies clearly defined including replacement, rework, and liquidated damages. Quality data sharing enables predictive analytics and continuous improvement.
Chapter 6: Regulatory and Policy Landscape — Value Creation and Destruction
Regulatory frameworks create, modify, or destroy storage value faster than market fundamentals. Continuous monitoring and adaptive strategy essential.
Federal Policy Environment (U.S.)
Inflation Reduction Act Implications: ITC extension to standalone storage (30% base + bonus adders) transformed economics. Domestic content bonus (10%), energy community bonus (10%), and low-income community bonus (10-20%) stack potentially doubling base credit. Qualification requirements complex; expert tax advisory essential. Prevailing wage and apprenticeship compliance mandatory for full credit; documentation burdens significant but manageable. IRA benefits scheduled through 2032+ providing decade-long policy visibility unprecedented in sector.
FERC Order 2222 Implementation: Enabling distributed and aggregated resources including storage to participate in wholesale markets. Implementation progress varies by RTO/ISO; some fully implemented, others delayed. Full implementation expands addressable market and revenue opportunities for smaller and distributed storage. Monitoring implementation status informs market entry timing.
Federal Permitting Reform: Potential legislation streamlining transmission and generation permitting would indirectly benefit storage by accelerating renewable buildout increasing storage demand. Bipartisan support but uncertain timeline. Permitting reform complementary to direct storage incentives; both needed for optimal market development.
State-Level Policy Variability
California: Leading storage market with aggressive procurement mandates, resource adequacy framework, and SGIP incentive program (winding down). CPUC proceedings continuously refining storage role in grid. Wildfire mitigation creating additional use cases. Regulatory complexity high but market maturity compensates.
New York: NYISO capacity market reforms recognizing storage value. VDER tariff enabling distributed storage compensation. Climate Leadership and Community Protection Act driving decarbonization mandate. Con Edison and other utilities incorporating storage into distribution planning. Market developing but less mature than California.
Texas: No state-level storage mandate but ERCOT market design creates organic economics. Legislative sessions periodically considering capacity market or reliability mechanisms; outcomes uncertain. Winterization requirements post-Uri adding cost but also value. Pure market-driven environment rewards operational excellence and punishes poor positioning.
Emerging Markets: Virginia, New Jersey, Massachusetts, Arizona, Nevada, and others adopting storage targets or incentives. Early-stage markets offer first-mover advantages but higher regulatory risk. Monitoring legislative and regulatory dockets identifies emerging opportunities before consensus forms.
International Policy Frameworks
European Union: REPowerEU accelerating storage deployment as energy security measure. EU Battery Regulation imposing sustainability, recycling, and passport requirements. Member state implementation varies creating fragmented market. Carbon Border Adjustment Mechanism affecting imported battery materials. EU market attractive but regulatory burden significant.
United Kingdom: Capacity Market providing long-term revenue certainty. Net Zero Strategy driving deployment targets. Ofgem regulatory reforms enabling storage participation across markets. Post-Brexit regulatory divergence creating both opportunities and complexities. UK market mature with established financing precedents.
Australia: National Battery Strategy targeting domestic manufacturing and deployment. State-level schemes (NSW, Victoria, Queensland) adding incentives. NEM reform introducing new market mechanisms for storage. Transmission expansion creating locational value opportunities. Australian market high-growth but regulatory evolution rapid.
Asia-Pacific: China dominant manufacturer and deployer with aggressive domestic targets. India PLI scheme incentivizing domestic manufacturing. Japan and South Korea supporting storage through grid modernization programs. Southeast Asia emerging markets with growing renewable penetration driving storage demand. APAC markets diverse requiring country-specific analysis.
Regulatory Risk Management
Change-in-Law Protections: Contracts and financing documents should include change-in-law provisions allocating regulatory risk appropriately. Force majeure definitions encompassing adverse regulatory changes. Termination rights or compensation mechanisms for material adverse changes. Negotiating protections easier ex-ante than litigating ex-post.
Regulatory Monitoring Capability: Dedicated regulatory monitoring function tracking legislation, rulemaking, and enforcement across relevant jurisdictions. Early warning systems identifying emerging risks and opportunities. Stakeholder engagement through industry associations and direct participation in proceedings. Regulatory intelligence competitive advantage informing timing and positioning decisions.
Scenario Planning: Modeling revenue impacts under alternative regulatory scenarios (base case, favorable reform, adverse change). Sensitivity analysis identifying break-even regulatory assumptions. Contingency plans for adverse scenarios including contract renegotiation, operational adjustment, or exit strategies. Scenario planning prevents reactive decision-making under pressure.
Chapter 7: Operational Excellence and Asset Management
Post-COD operational execution determines whether projected returns materialize.
Operations and Maintenance Strategy
O&M Contract Structure: Comprehensive O&M agreements with experienced providers preferred over self-performance for most investors. Contract scope includes preventive maintenance, corrective repairs, performance monitoring, warranty administration, and reporting. Performance guarantees with liquidated damages for availability and efficiency shortfalls. Term aligned with debt tenor or project life. O&M provider financial strength and technical capability verified; provider bankruptcy creates operational crisis.
Predictive Maintenance Implementation: Data-driven maintenance optimizing availability and minimizing cost. Battery health monitoring detecting degradation anomalies before failure. Thermal imaging identifying hot spots. Electrical testing verifying connection integrity. Predictive analytics scheduling maintenance during low-value periods maximizing revenue capture. Maintenance data feeding degradation model refinement improving forecasting accuracy.
Spare Parts Management: Critical spare inventory balancing availability against carrying cost. Strategic spares identified through FMEA analysis. Lead time assessment informing stocking levels. Obsolescence monitoring ensuring long-term parts availability. Spare parts agreements with OEMs securing supply commitments. Inventory management system tracking usage and replenishment.
Software and Firmware Updates: Regular updates maintaining security, compliance, and performance optimization. Update testing in staging environment before production deployment. Rollback procedures for failed updates. Cybersecurity patches prioritized. Update schedule coordinated with revenue-maximizing dispatch avoiding unnecessary downtime.
Performance Monitoring and Optimization
Real-Time Analytics Platform: Comprehensive monitoring integrating BMS, EMS, SCADA, and market data. Dashboards tracking KPIs: availability, efficiency, degradation rate, revenue capture, and safety metrics. Alert systems flagging anomalies for investigation. Historical data archiving enabling trend analysis and model validation. Platform scalability accommodating portfolio growth.
Dispatch Optimization: Algorithmic dispatch maximizing revenue across stacked value streams. Optimization considers price forecasts, degradation costs, maintenance schedules, and contractual obligations. Machine learning improving forecasts and optimization over time. Human oversight maintaining strategic alignment and exception handling. Optimization performance benchmarked against theoretical maximum identifying improvement opportunities.
Degradation Tracking and Forecasting: Continuous monitoring comparing actual degradation against modeled projections. Variance analysis triggering operational adjustments or model recalibration. Augmentation planning informed by actual degradation trajectory rather than static assumptions. Degradation data supporting warranty claims when performance falls below guaranteed levels. Transparent degradation reporting to investors and lenders maintaining trust.
Asset Management and Portfolio Optimization
Portfolio-Level Dispatch Coordination: Multi-asset optimization capturing synergies unavailable to standalone projects. Geographic diversification smoothing aggregate revenue. Coordinated bidding reducing self-cannibalization. Shared services reducing O&M cost per unit. Portfolio analytics identifying best practices and underperformers. Centralized reporting enabling efficient investor and lender communication.
Contract Renegotiation and Optimization: Periodic review of contractual arrangements identifying improvement opportunities. Capacity contract renewals at improved terms as market matures. Merchant revenue optimization through updated dispatch strategies. O&M contract benchmarking against market rates. Tax equity partnership optimization reflecting changed circumstances. Proactive contract management extracts value passive ownership misses.
Technology Refresh and Repowering: Evaluating mid-life technology upgrades improving performance or extending asset life. Partial repowering replacing degraded modules while retaining functional components. Complete repowering when economics justify full replacement. Technology refresh timing optimized balancing remaining asset life against upgrade cost and benefit. Repowering decisions integrated with augmentation strategy avoiding redundant investment.
Exit Strategy Planning: Continuous evaluation of exit opportunities maximizing investor returns. Strategic sales to utilities, IPPs, or infrastructure funds seeking operating assets. Portfolio sales achieving scale premium. Recapitalizations returning capital while retaining upside. IPO or SPAC combinations for scaled platforms. Exit timing aligned with market cycles and contract milestones. Exit preparation ongoing not episodic; organized data rooms and clean documentation accelerate transactions and improve pricing.
Conclusion: Disciplined Capital Deployment in Transformative Infrastructure
Battery storage represents genuine infrastructure transformation—not speculative technology bet. The asset class has achieved commercial viability, regulatory recognition, and institutional acceptance. But viability doesn't imply simplicity or guaranteed returns. Storage rewards disciplined investors who understand its unique characteristics and punishes those applying traditional infrastructure heuristics uncritically.
The investors succeeding in this space share common attributes: they respect technology complexity engaging specialized expertise rather than assuming equivalence to generation. They model revenue stacks honestly acknowledging saturation and regulatory risk rather than extrapolating current margins indefinitely. They structure capital appropriately matching debt to contracted cash flows and equity to merchant upside. They manage supply chain proactively securing allocation and quality rather than hoping spot markets cooperate. They monitor regulatory landscapes continuously adapting strategy as rules evolve. And they operate assets excellently recognizing that post-COD execution determines whether projected returns materialize.
Battery storage isn't easy money. It's earned money—earned through analytical rigor, operational discipline, and patient capital deployment aligned with genuine infrastructure value creation. The energy transition needs this capital. The grid needs this infrastructure. Investors who bring discipline alongside conviction will capture returns commensurate with the value they create.
Deploy capital accordingly. The opportunity is real. So is the complexity. Master both.
Frequently Asked Questions (FAQs)
What is the typical IRR range for battery storage investments and what drives variance?
Unlevered IRRs typically range 8-18% depending on revenue mix, market, technology, and contracting structure. Contracted-heavy projects in mature markets (PJM capacity, UK CM) target 8-12% with lower volatility. Hybrid contracted-merchant projects target 12-15%. Pure merchant projects in volatile markets (ERCOT, CAISO) target 15-18%+ with corresponding downside risk. Key IRR drivers: contracted revenue percentage and counterparty quality, market price volatility and spread, degradation rate and augmentation cost, capital cost ($/kWh installed), operating expense efficiency, and tax incentive capture. IRR alone insufficient; risk-adjusted metrics (Sharpe ratio, probability-weighted returns) better capture storage's asymmetric risk profile. Benchmark against comparable infrastructure alternatives adjusting for technology and market risk premium.
How should investors think about battery degradation and augmentation in financial models?
Model degradation as throughput-dependent function rather than simple time-based decline. Use manufacturer warranty as floor but model expected degradation based on independent engineer assessment of projected cycling profile, temperature, and chemistry. Augmentation timing and cost should be explicit line items not buried contingencies. Typical augmentation at year 8-12 for daily-cycling LFP systems; earlier for aggressive cycling or NMC chemistry. Augmentation cost assumptions should reflect expected technology cost declines (historically 10-15%/year) balanced against inflation and supply chain dynamics. Sensitivity analysis around degradation rate (+/- 20%) and augmentation cost (+/- 30%) reveals IRR sensitivity. Reserve funding mechanism (upfront reserve, refinance, vendor financing) selected based on capital efficiency and risk tolerance. Degradation monitoring and model recalibration throughout operations ensures augmentation planning remains accurate.
What are the key differences between investing in standalone storage versus co-located storage with solar/wind?
Standalone storage offers operational flexibility accessing full revenue stack independently. Can optimize charging from grid when prices lowest regardless of renewable generation. Eligible for standalone ITC under IRA. Higher revenue potential but also higher market risk. Co-located storage shares interconnection reducing cost and timeline. May qualify for enhanced ITC if meeting coupled charging requirements. Revenue partially constrained by renewable generation profile unless grid charging enabled. Simpler permitting in some jurisdictions. Co-location advantageous when interconnection constrained or renewable PPA includes storage component. Standalone preferable when market arbitrage primary revenue driver. Hybrid configurations increasingly common capturing both advantages. Choice depends on specific market, interconnection, contract, and tax circumstances; neither universally superior.
How do investors assess and mitigate supply chain risk for battery storage projects?
Supply chain risk assessed across four dimensions: geographic concentration, price volatility, ESG/compliance exposure, and manufacturing capacity adequacy. Mitigation strategies include: multi-supplier qualification reducing single-source dependency; long-term framework agreements securing allocation and pricing predictability; index-linked pricing with collars balancing fairness and certainty; domestic content qualification capturing IRA bonuses while diversifying away from China concentration; strategic inventory buffering critical components; supplier financial health monitoring preventing disruption from vendor distress; and contractual protections including liquidated damages, termination rights, and alternative sourcing options. Supply chain due diligence extends beyond tier-1 integrator to cell manufacturer and upstream mineral suppliers. Engagement with industry associations and government trade agencies provides early warning of emerging disruptions. Supply chain risk management is continuous process not point-in-time assessment.
What due diligence items are unique to battery storage versus traditional renewable energy investments?
Storage-specific due diligence includes: battery degradation modeling validation by independent electrochemical engineer; BMS and controls software assessment for sophistication and vendor viability; thermal management system design review for adequacy and redundancy; safety certification verification (UL 9540A, NFPA 855 compliance) and insurance carrier acceptance; augmentation strategy and funding mechanism evaluation; revenue stack modeling with market-specific saturation and regulatory risk assessment; O&M provider technical capability verification for storage-specific expertise; warranty terms analysis covering degradation guarantees and remedy mechanisms; supply chain traceability for ESG and trade compliance; and end-of-life disposition planning including recycling economics and regulatory obligations. Traditional renewable DD focuses on resource assessment, PPA credit, and construction execution; storage DD emphasizes electrochemical performance, market design dependency, and technology lifecycle management. Engaging advisors with dedicated storage experience prevents applying inappropriate renewable templates to fundamentally different asset class.
Share
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0